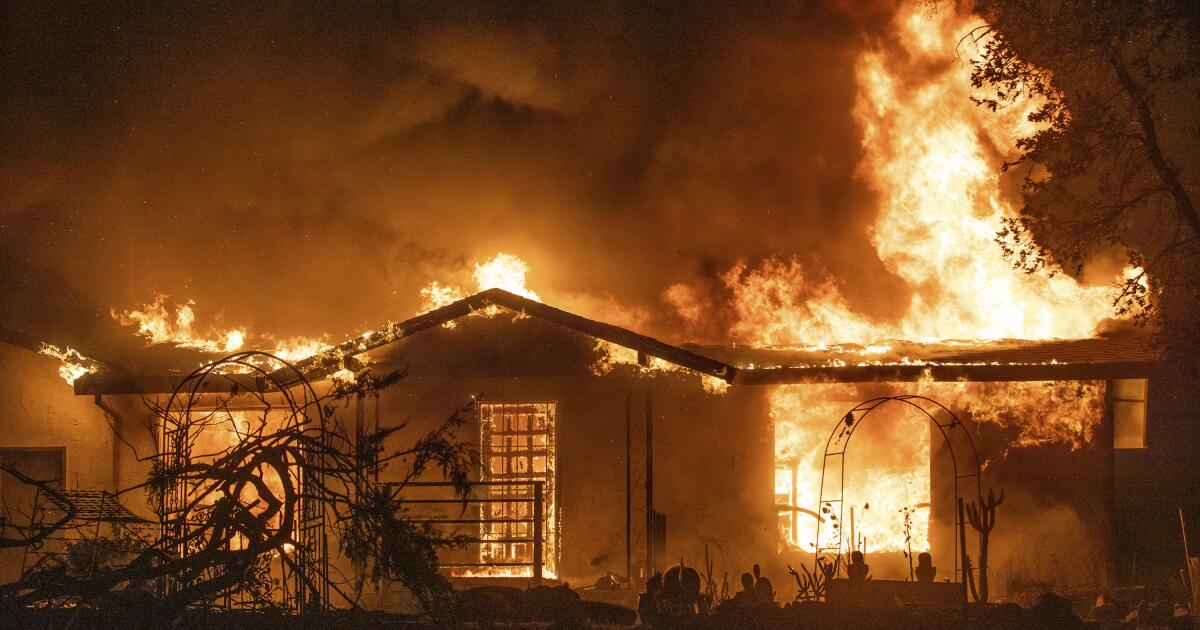
Insurance coverage corporations collected greater than $150 billion in premiums from California householders over the past 25 years and loved income at 4 occasions the nationwide common. Now they’re demanding an unprecedented bailout from the California Legislature as the worth of constant to do enterprise right here within the wake of wildfire losses.
Business lobbyists are reportedly negotiating with lawmakers, Insurance coverage Commissioner Ricardo Lara and Gov. Gavin Newsom’s workplace towards a deal that will be unveiled within the final weeks earlier than the Legislature adjourns on Sept. 14. The {industry}’s plan would advance its decades-long drive to undermine the protections of Proposition 103, the insurance coverage reform measure handed by voters 35 years in the past. The proposal would enable insurance coverage corporations to hike charges with out full transparency or justification; drive policyholders to imagine the staggering prices of insurers’ backup protection for surprising losses; and use secret algorithms to set premiums.
These at the moment unlawful practices are prone to increase property insurance coverage premiums by 40% or extra. Many extra clients may very well be compelled into the California FAIR (Truthful Entry to Insurance coverage Necessities) Plan, a state-created, industry-controlled affiliation that gives much less beneficiant, last-resort protection at larger costs.
Worse, the proposed bailout relieves insurance coverage corporations of their duty to cowl all losses underneath the FAIR Plan, forcing the state’s policyholders to shoulder the burden via obligatory surcharges on their insurance coverage payments. The proposal would incentivize insurance coverage corporations to push their riskiest clients into the FAIR Plan and make different policyholders subsidize their claims. Insurers would retain solely their most worthwhile clients.
Some lawmakers have prompt that capitulating to the {industry}’s calls for for deregulation, vastly larger premiums and 0 threat is critical to lure insurance coverage corporations again to California. Firms similar to State Farm, Allstate and Farmers have orchestrated an insurance coverage scarcity within the state by refusing to promote new insurance policies and improperly dumping present clients. However the corporations’ proposal doesn’t assure that anybody who desires to purchase insurance coverage protection will likely be in a position to take action.
Nor has surrendering to {industry} calls for labored in Florida. Below Gov. Ron DeSantis, charge regulation is weak, insurers are opaque and firms are allowed to move on the price of reinsurance and impose surcharges on policyholders if the state’s FAIR Plan equal falls quick. And but home-owner premiums are two to a few occasions larger than in California, the proportion of policyholders with last-resort insurance coverage is 5 occasions better, and firms are quickly abandoning the state anyhow.
Below the California Structure, the Legislature is barred from amending the phrases of Proposition 103 besides to additional the initiative’s functions. Courts have repeatedly invalidated laws that weakens these reforms, because the {industry}’s newest proposal does. No matter their private views, lawmakers should respect the voters’ will and demand that insurance coverage corporations do the identical.
By ready till the final days of legislative enterprise to barter such a bailout, lawmakers are cynically trying to bypass public scrutiny and debate whereas undermining the credibility of their establishment. Because the Legislature’s 1996 deregulation of utility charges confirmed, poorly vetted, industry-backed proposals can grow to be expensive debacles for California shoppers and taxpayers.
There are lots of authentic methods to handle the impression of wildfires and different excessive climate occasions with out bailing out the {industry} or permitting it to keep away from transparency and accountability. Our leaders ought to take the time to look into them.
For instance, cash from a proposed local weather bond and the state’s cap-and-trade program may very well be deployed to assist householders take precautions that scale back the danger of loss from excessive occasions similar to wildfires. Reasonably than permitting insurance coverage corporations to make land use coverage via charges, state and native authorities should develop rational guidelines to information development in high-risk areas. And insurance coverage corporations ought to be given a deadline to cease insuring and investing within the oil and gasoline corporations which are fueling local weather change.
Lastly, as a situation for the privilege of promoting any form of insurance coverage in California, corporations should be required to cowl all householders who’ve taken applicable measures to guard their property. And insurers that select to go away the state shouldn’t be allowed to return for 5 years. Firms that acquire our premiums for many years after which all of a sudden resolve they don’t need to obey our legal guidelines shouldn’t be allowed to do enterprise within the largest and most profitable insurance coverage market within the nation.
Harvey Rosenfield is the founding father of Shopper Watchdog and the creator of Proposition 103.
Supply hyperlink